

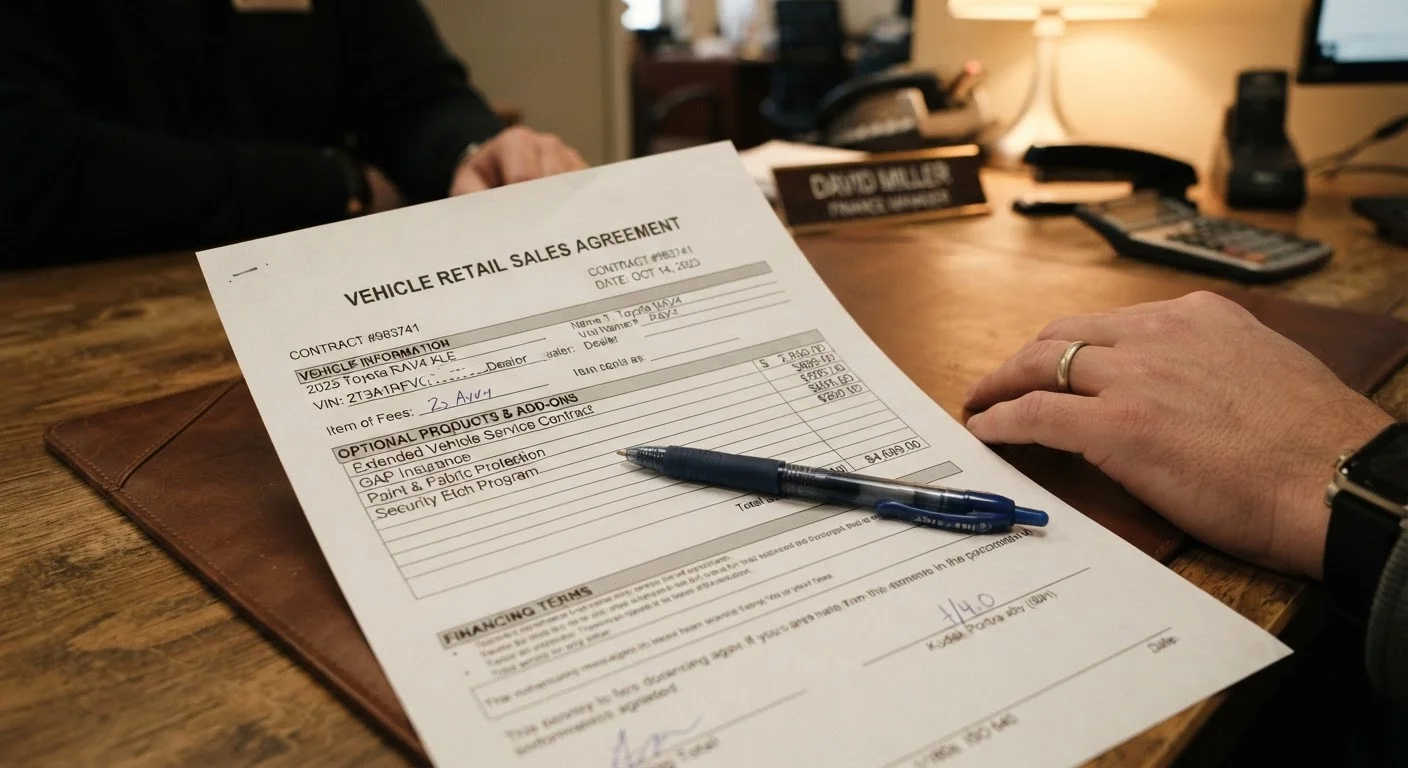
What Counts as a Dealer Add-On
Dealer add-ons fall into three broad categories, and understanding the distinction helps you evaluate each line item on your buyer's order with clarity.
- Mandatory fees: Documentation fees, dealer preparation charges, and advertising fees are common examples. These appear on nearly every transaction, though their amounts differ by dealership and state regulations.
- Pre-installed accessories: Items physically attached to the vehicle - wheel locks, floor mats, cargo nets, roof racks - that the dealer has already installed before you visit. These are often presented as non-removable, though that claim is worth questioning.
- Finance office products: Extended service contracts, GAP coverage (Guaranteed Asset Protection), paint sealant, and tire-and-wheel protection are typically introduced during the finance and insurance (F&I) stage of the deal.
Each category carries different negotiating dynamics. For a closer look at how add-ons are presented in the finance office, see our breakdown of finance office extras.
How Add-Ons Inflate the Final Price
The vehicle's advertised price - whether that's MSRP or a dealer's listed price - typically does not include add-ons. When you review the buyer's order, add-ons appear as separate line items that increase the capitalized cost of the deal. Understanding what each listed price figure means before you visit a dealership gives you a cleaner baseline for comparison.
$1,000-$3,000+
Typical range of dealer add-ons per transaction
Industry observers and consumer advocates commonly cite this range as the amount add-ons can add to a vehicle's transaction price, though figures vary by dealership and market conditions.
Varies by state
Documentation fee regulation across U.S. states
Some states cap documentation fees by law while others leave them unregulated, resulting in wide variation from under $100 to over $700 for the same administrative function.
The compounding effect is most significant when add-ons are financed. A $1,200 paint protection package financed over 60 months at a typical auto loan rate results in a total cost that exceeds the face price once interest is included. This is why evaluating add-ons in cash terms - not monthly payment terms - gives a more accurate picture. For a broader framework on total outlay, see our overview of true ownership costs.
Evaluating Which Add-Ons Are Negotiable
Not every add-on deserves equal scrutiny. A practical approach is to assign each item to one of three categories: likely fixed, negotiable in price, or removable entirely.
Documentation fees are often fixed by dealership policy or state law but can sometimes be offset by negotiating the vehicle price downward. Market adjustment fees - markups above MSRP applied to high-demand models - are dealer-set and negotiable, though leverage depends on vehicle availability. Manufacturer incentives and dealer cash can sometimes counterbalance these markups when they exist.
Paint sealant, fabric protection, and nitrogen-filled tires are widely considered low-cost treatments sold at a significant margin. They are generally removable from the deal. Pre-installed physical accessories present a slightly different challenge - if the dealer has already installed them, removal may not be practical, but their price is usually negotiable.
Ask for the Buyer's Order Early
Request a complete, itemized buyer's order before entering the finance office. This document lists every charge, including add-ons, and gives you time to review each line item without the time pressure of a closing environment. Identifying add-ons early in the process puts you in a stronger position to question or decline them.
For context on the line between accessories and more involved vehicle modifications, see our guide to accessories versus modifications.
Building Add-Ons Into Your Price Comparison
To compare deals accurately across dealerships, you need an apples-to-apples total. Request an itemized out-the-door quote that lists the vehicle price, all add-ons, fees, taxes, and registration costs separately. This lets you strip out non-vehicle charges and compare the effective vehicle price across multiple offers.
A low asking price can be misleading when one dealer bundles thousands of dollars in add-ons while another does not. The dealer with the higher advertised price may actually represent a lower total cost once add-ons are accounted for.
Out-the-Door Price vs. Sticker Price
The "out-the-door" price is the total you pay at signing, including the vehicle price, all dealer add-ons, applicable taxes, registration fees, and documentation charges. Always request this figure in writing before comparing dealers. A sticker price or internet price quote typically excludes several of these cost layers.
Once you have a clean vehicle price, you can evaluate financing separately. Understanding how loan terms interact with the financed amount is covered in our guide to auto financing rates and terms. Add-ons financed over longer terms are among the less visible ways total cost grows beyond what monthly-payment comparisons reveal.
This article is for general informational and educational purposes only and does not constitute financial or legal advice. Consult a qualified professional for guidance specific to your situation.


