

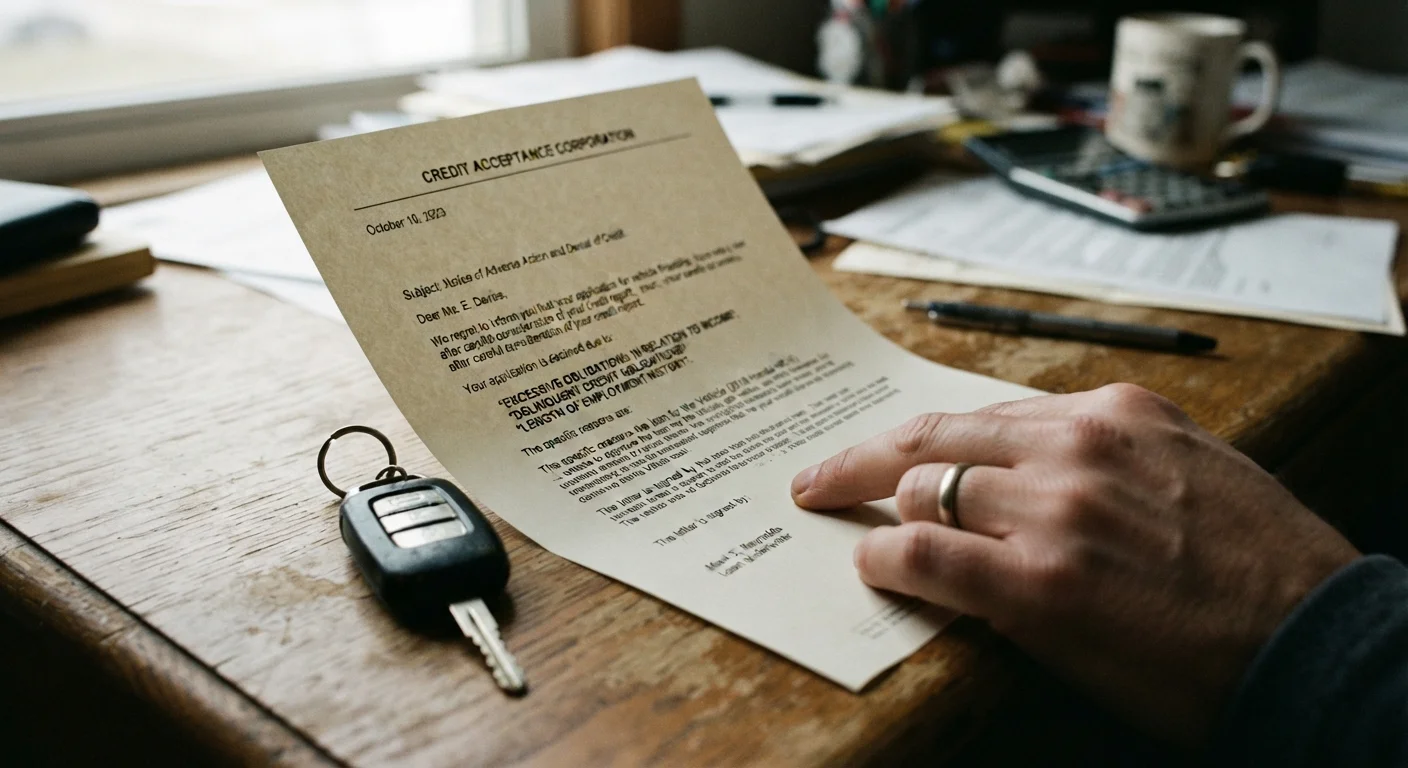
What the Adverse Action Notice Actually Is
When a lender declines your auto loan application, federal law - specifically the Equal Credit Opportunity Act (ECOA) and the Fair Credit Reporting Act (FCRA) - requires them to send you an adverse action notice. This is not a form rejection; it is a structured disclosure with legal standing, and it carries information you should treat as a diagnostic report rather than a dead end.
The notice must include the name and contact information of the lender, a statement of your right to request a free copy of your credit report within 60 days, and - most critically - the specific reasons the application was declined. Those reasons are communicated through standardized codes or plain-language statements that correspond to underwriting criteria the lender evaluated. To understand what those criteria actually mean, review how lenders read your credit report before interpreting any reason code.
You Have the Right to Know Why
Federal law gives you the explicit right to know the specific reasons behind any credit denial. If the notice you received contains only vague language without specific reason codes, you can request a written statement of reasons directly from the lender within 60 days of receiving the notice. Lenders are legally obligated to provide this. Do not proceed without it - without specific reasons, any remediation effort is guesswork.
Decoding the Most Common Reason Codes
Lenders are required to list their top reasons - typically up to four - in descending order of impact. The first reason listed carried the most weight in the decision. Here is what the most frequently cited codes actually signal:
- Delinquent past or present credit obligations: Late payments appear on your report and indicate payment risk. Even a single 30-day late mark can affect scoring models used in auto underwriting.
- Insufficient credit history: Thin files - few accounts or a short average age of credit - give lenders little predictive data. This is not the same as bad credit; it is absent credit.
- Excessive obligations in relation to income: Your debt-to-income ratio (DTI) - total monthly debt payments divided by gross monthly income - exceeded the lender's threshold. This is an income or load problem, not always a credit score problem.
- Too many inquiries in the past 12 months: Multiple hard inquiries within a short window can signal credit-seeking behavior that lenders treat as elevated risk.
- Amount owed on revolving accounts too high: High credit utilization - the percentage of revolving credit limits in use - suppresses scores significantly. Paying down balances is typically the fastest way to address this.
- No recent installment loan information: Lenders prefer to see prior experience managing installment debt. A lack of prior auto or personal loan history can create uncertainty.
For precise definitions of terms like DTI, utilization, and installment credit, see the auto loan terminology glossary.
Order of Reason Codes Matters
Lenders list adverse action reasons in descending order of influence on the decision. If your notice lists four reasons, the fourth had the least impact. Focus your effort on reasons one and two first - resolving the primary drivers will have disproportionate effect on your creditworthiness relative to addressing minor factors.
How to Respond Strategically
A decline letter is only useful if you act on it methodically. Work through the steps below before reapplying to any lender.
Request your credit report immediately
The adverse action notice entitles you to a free credit report from the bureau the lender used, within 60 days of the notice date. Request it directly from that bureau. Do not rely solely on score-monitoring apps - you need the full tradeline detail, including payment history, account ages, balances, and any public records or collections entries.
Match each reason code to a specific item on your report
Read the reason codes line by line, then locate the corresponding data on your credit report. A code citing delinquency should point you to specific late payment entries. A code about utilization should direct you to the balances versus limits on your revolving accounts. Do not skip this matching step - it prevents you from working on the wrong problem.
Dispute any verified errors in writing
If you find inaccurate information - an account that is not yours, an incorrectly reported late payment, or a balance that does not reflect a payoff - file a formal dispute with the reporting bureau under FCRA procedures. Keep documentation of the dispute submission and any responses. Bureaus are required to investigate within 30 days under standard rules.
Build a targeted remediation plan around the top reason
Prioritize the first reason listed - it had the greatest weight. If the primary issue is high utilization, calculate how much you need to pay down to reach the commonly cited threshold of 30% or below per account. If the issue is DTI, model whether reducing existing debt or increasing documented income changes the ratio materially. Avoid broad, unfocused efforts that spread your energy without moving the key metric.
Re-evaluate the loan structure before reapplying
A larger down payment reduces the loan-to-value (LTV) ratio and lowers the lender's collateral risk - this can offset moderate credit weaknesses. A shorter loan term also reduces lender exposure and may shift an application from marginal to approvable with the same credit profile. Consider whether adjusting the vehicle price point changes the application math in your favor before submitting again.
Once you have addressed the primary reason codes, use the credit readiness checklist to verify your standing before your next application. Also be aware of the credit habits that quietly hurt auto loan applications - some patterns undermine your profile even when your score looks adequate on the surface.
This article provides general financial education and is not personalized financial or legal advice. For guidance tailored to your specific credit situation, consult a qualified financial professional.


