

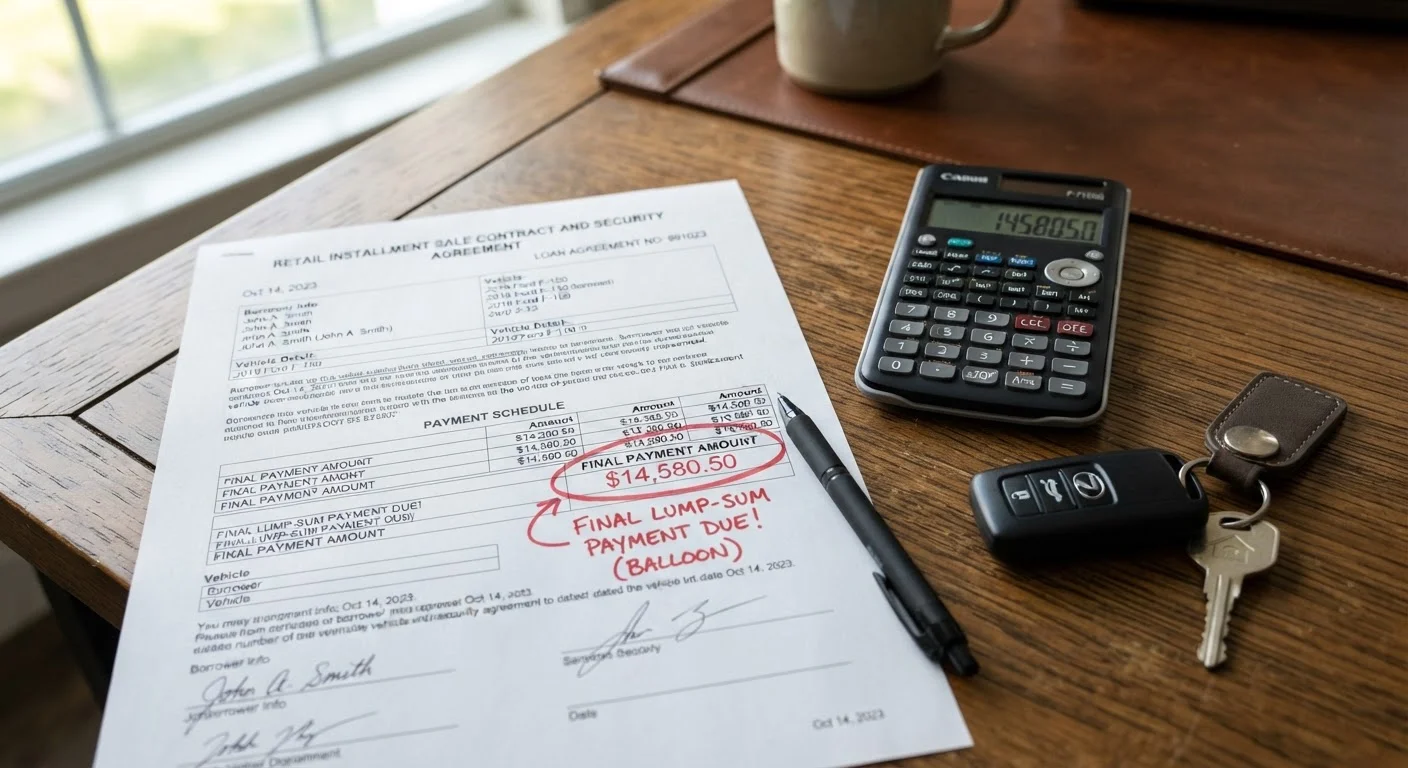
How a Balloon Loan Is Structured
In a conventional fully amortizing auto loan, every monthly payment chips away at both interest and principal so that the final payment retires the debt entirely. A balloon loan works differently: the lender calculates payments as if the loan will run for a much longer term - say, 84 months - but the contract matures earlier, often at 36 or 48 months. The gap between those two timelines produces the balloon: the principal that would have been paid in those extra years is instead bundled into one final lump sum.
For example, consider a $45,000 truck financed with a 5-year balloon structured on a 10-year amortization schedule. Monthly payments reflect the longer schedule, keeping them modest. But at month 60, the borrower owes whatever principal remains - potentially $15,000-$20,000 or more - in a single payment. That is the balloon.
Understanding how amortization schedules work is essential before evaluating any balloon proposal, because the payment math obscures how slowly the principal reduces in early months.
20-50%
Typical balloon payment as share of original loan
Industry financing structures commonly defer this range of the original principal balance to the final balloon payment date, depending on term length and amortization schedule used.
15-25%
Average first-year vehicle depreciation
Most new vehicles lose roughly 15-25% of value in the first year, a key factor in assessing whether a balloon balance will exceed the car's resale value at maturity.
60-84 months
Common amortization schedules used to set balloon payments
Lenders frequently use longer notional amortization windows to calculate the periodic payment, with the actual loan term ending well before the schedule concludes.
Where Balloon Financing Commonly Appears
Balloon structures are not typical in standard consumer auto loans for passenger cars, where fully amortizing loans dominate. They appear most frequently in three contexts:
- Commercial vehicle financing: Fleet operators and small businesses use balloon loans to match payment timing to cash flow cycles or equipment replacement schedules.
- RV and camper loans: Because RVs carry large price tags and longer useful lives, lenders sometimes offer balloon options to make payments accessible. Buyers exploring the auto loan versus lease comparison for RVs should examine whether a balloon is embedded in the offer.
- Classic and specialty vehicles: When resale values are less predictable, some private lenders structure balloon notes that assume the borrower will sell the vehicle near term-end.
In each case, the lender's motivation is consistent: reduce default risk by lowering the periodic payment burden while preserving the right to collect the full principal balance.
Always Request the Full Amortization Schedule
Before signing any balloon loan, ask the lender for a complete amortization table showing the principal balance at every payment date, including the final balloon amount. This document makes the deferred balance and total interest cost fully transparent. If a lender is unwilling to provide it, treat that as a red flag.
The Core Risks Buyers Must Understand
The fundamental risk is the depreciation gap. Vehicles lose value continuously, and if a vehicle's market value at balloon maturity falls below the amount still owed, the borrower is upside-down. They cannot sell the vehicle for enough to cover the balloon and must either absorb the shortfall from savings or refinance at potentially unfavorable terms.
Loan term length directly shapes total interest paid, and balloon loans are no exception. Because a large portion of the principal is deferred, interest accrues on a higher outstanding balance for longer - pushing total financing cost above what a standard loan of the same rate would carry.
A secondary risk is refinancing uncertainty. When the balloon comes due, the borrower's credit profile, prevailing interest rates, and lender appetite may all differ from when the original loan was signed. Assuming refinancing will be easy or inexpensive is a planning error that can create serious financial pressure.
Balloon Loans vs. Lease Structures
Balloon payment loans and vehicle leases both reduce periodic payments by deferring value - but they operate under different legal frameworks. In a lease, you do not own the vehicle; the residual is a manufacturer-backed figure, and you simply return the car or buy it at term end. In a balloon loan, you hold title throughout, bear all depreciation risk, and are contractually obligated to pay the balloon regardless of what the vehicle is worth. Understanding this distinction is critical when comparing financing offers.
This article is for general informational purposes only and does not constitute personalized financial, legal, or tax advice. Consult a qualified financial professional before making decisions about your specific financing situation.
Evaluating Whether a Balloon Loan Fits Your Situation
A balloon loan can be rational under specific conditions: the borrower has high confidence they will sell or trade the vehicle before the balloon date, has a credible plan for the lump-sum payment, or operates in a business context where cash flow timing makes deferred principal genuinely advantageous.
Before agreeing to any balloon structure, run these comparisons:
- Calculate the total amount paid under the balloon loan versus a fully amortizing loan at the same rate - including the balloon itself.
- Model the vehicle's likely depreciation curve and compare it to the projected balloon balance. Sites publishing industry depreciation data can provide benchmarks.
- Review your credit profile and approval outlook to assess how refinancing options might look at balloon maturity.
- Read the contract for prepayment penalties and what happens if you want to exit early.
For a broader context on how all the rate and term variables interact, the complete field guide to auto financing rates and terms covers the full landscape. Buyers who understand the full financing structure - not just the monthly payment - are better positioned to recognize when a balloon loan is a useful tool versus a costly trap.


