

What DTI Reveals That Credit Scores Don't
Credit scores are backward-looking instruments - they summarize how reliably you've handled debt in the past. Debt-to-income ratio is forward-looking: it tells a lender whether your current income can actually absorb a new monthly payment without creating undue financial strain.
These two metrics measure entirely different risks. A borrower who managed a modest income carefully for years might carry an excellent credit score, but if their obligations have since expanded - through a new mortgage, a personal loan, or rising minimum card payments - their DTI may tell a more cautious story. Lenders evaluating auto loan applications routinely review both signals because approval based on credit score alone wouldn't account for a borrower's real-time budget constraints.
Understanding how lenders read your full credit profile is foundational here. See how auto lenders read your credit report for a deeper look at what gets weighted in underwriting.
DTI Is Not Reported on Your Credit File
Unlike your credit score, your debt-to-income ratio is not a standing figure stored in any credit bureau database. Lenders calculate it at the time of application using your reported debts and income documentation you provide. This means DTI can change significantly between applications - for better or worse - based on recent financial activity.
How Lenders Calculate and Apply Your DTI
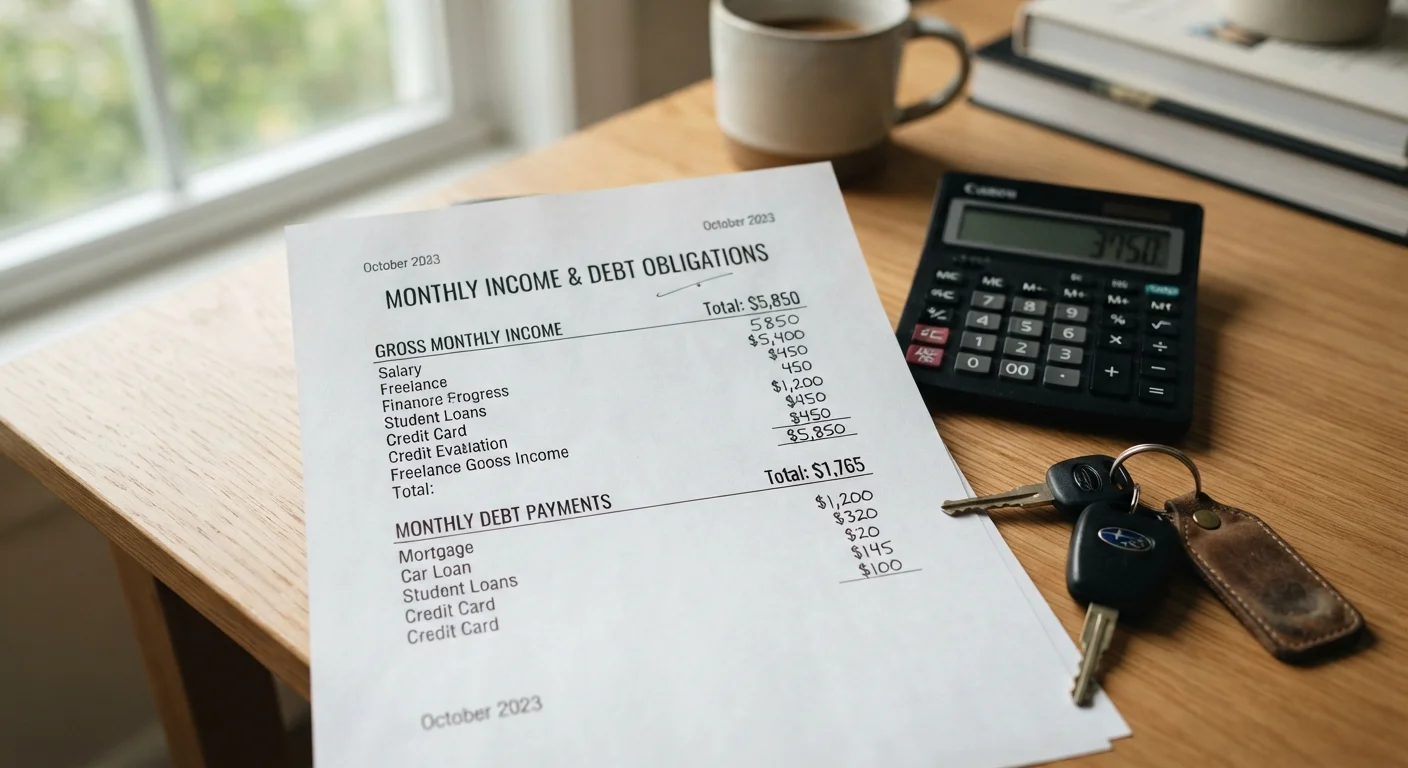
The calculation itself is straightforward. Lenders sum all minimum monthly debt obligations reported on your credit file - auto loans, student loans, credit card minimums, mortgage or rent payments, personal loans - and divide that total by your verified gross monthly income. The result, expressed as a percentage, is your back-end DTI.
Where lenders differ is in how they weight DTI against other underwriting factors. Some lenders apply hard cutoffs: a DTI above a defined threshold triggers automatic decline regardless of credit score. Others use a risk-adjusted model where a high DTI elevates the rate offered rather than blocking approval entirely. In either case, the proposed new vehicle payment is typically factored into the DTI calculation before a decision is made, which means the loan amount you're requesting directly affects your approval odds.
This interaction between loan size and DTI connects directly to another ratio lenders monitor closely. The loan-to-value ratio affects approval and rate decisions in tandem with DTI, particularly when the financed amount is large relative to the vehicle's market value.
43%
Common maximum DTI threshold for loan approval
Many traditional lenders use 43% as an upper boundary for back-end DTI when evaluating installment loan applications, including auto loans, though individual lender policies vary.
~28%
Typical preferred front-end DTI ceiling
Industry underwriting guidelines often reference a front-end DTI (housing costs alone) of around 28% as a benchmark for financially comfortable borrowers, though auto lenders focus primarily on back-end DTI.
Improving Your DTI Before Applying
There are two variables in the DTI formula: total debt and gross income. Improving your ratio requires moving at least one of them in the right direction before submitting a loan application.
On the debt side, paying down revolving balances - particularly credit cards - reduces the minimum monthly payment that feeds into your DTI calculation. Eliminating smaller installment loans before applying can also have a meaningful effect, even when the remaining balances are modest.
On the income side, verifiable income matters. Lenders generally require documentation - pay stubs, tax returns, or bank statements - to confirm earnings. Side income, freelance revenue, or rental income may be counted if it's consistent and documentable, though policies vary by lender.
One important boundary: a larger down payment does not reduce your DTI, because DTI is calculated on monthly payment obligations, not loan balances. A higher down payment reduces the loan amount (and therefore the monthly payment), which has an indirect DTI effect - but the primary lever remains your existing debt load relative to income.
Run Your Own DTI Calculation First
Before visiting a dealership or applying for financing, calculate your current back-end DTI using your gross monthly income and your credit report's minimum payments. Then add the estimated monthly payment for the vehicle you're considering. Knowing your projected post-loan DTI in advance lets you adjust your target loan amount - or pay down existing debt - before a lender sees the numbers.
For context on how your credit profile interacts with the rates you're offered, how credit score tiers translate into rate ranges provides useful framing alongside what you now understand about DTI.
This article is for general informational and educational purposes only and does not constitute personalized financial or lending advice. Consult a qualified financial professional regarding decisions specific to your circumstances.


